
The Salmon Credit Line Philippines pitch sounds almost too clean: no annual fee, a limit of up to ₱250,000, and up to 62 days to pay without interest. Here is the part the billboards skip. That 62-day window only applies to purchases made through QR Ph or the Salmon Card, it only kicks in when you pay your full statement balance on time, and the clock starts at your billing cycle, not at the moment you tap to pay. Transfer cash to GCash or your bank account and interest starts that same day.
Salmon launched its “Bank On It” campaign with Gretchen Ho and Sam YG in 2025. A year later, the company has a bigger credit limit, two fresh funding announcements, and around 9 million app downloads. So instead of rehashing the launch, this explainer breaks down how the product works in practice, where the catches are, and whether the bank behind it deserves your trust.
- Salmon Credit Line Philippines at a Glance
- How the 62-Day Grace Period Works
- The Catch: Salmon Credit Line Cash Transfer Interest
- Salmon Credit Line vs Credit Card
- Is Salmon Bank Legit? What Changed in 2026
- Salmon Bank PDIC Insured Deposits and Time Deposit Rates
- How to Apply for Salmon Credit Line
- TechPatrol Verdict
- Frequently Asked Questions
Salmon Credit Line Philippines at a Glance
| Feature | What You Get |
|---|---|
| Product type | Revolving credit line (borrow, repay, reuse) |
| Salmon credit line credit limit | Up to ₱250,000 (was up to ₱100,000 at the 2025 launch) |
| Annual fee | None |
| Interest-free period | Up to 62 days on purchases, if full statement balance is paid by due date |
| Where it works | QR Ph merchants, Visa/Mastercard merchants via physical or virtual Salmon Card |
| Cash transfers | Allowed to banks and e-wallets via InstaPay; interest accrues from day one |
| Salmon credit line interest rate | Set per customer based on profile and credit history |
| Minimum payment | Required monthly to keep the line active |
| Application | Through the Salmon app, decisions in as fast as 10 minutes |
How the 62-Day Grace Period Works
Think of the Salmon Credit Line as a credit card that lives inside an app. Salmon runs it on monthly billing cycles. Every purchase you make during a cycle lands on one statement, and that statement has a due date. Pay the whole statement balance by that date and you pay zero interest on those purchases.
The “up to 62 days” figure is the best-case scenario. It assumes you buy something on the first day of your billing cycle. That purchase rides the full cycle, then the extra days until the due date. Buy the same item near the end of the cycle and your interest-free window shrinks, because the statement closes soon after and the due date arrives on its usual schedule. Salmon says this outright in its own explainer: the later in the cycle you spend, the shorter your free ride.
In practice, a disciplined user can keep rolling purchases interest-free month after month. Salmon markets this as credit you can use “for free forever,” with an asterisk. The asterisk is you. Miss the full payment, pay only the minimum, or carry a balance, and interest applies.
A practical Filipino use case: you buy a ₱12,000 rice cooker and groceries at a mall that accepts QR Ph on the 2nd of your cycle. Your salary arrives on the 15th and 30th. You get one full cycle plus the due-date gap to clear the bill from two paydays instead of one. That breathing room is the real value here.
The Catch: Salmon Credit Line Cash Transfer Interest
This is where most users get burned. The Salmon app lets you transfer part of your available limit to any InstaPay-enabled bank or to an e-wallet like GCash. It feels like the same credit line. It is not treated the same way.
Salmon classifies these transfers as cash transactions. Cash transactions never get a grace period. Interest accrues from the date of the transfer, the same way a credit card cash advance works. Withdrawing cash using the card follows the same rule.
So if your plan is “transfer ₱20,000 to GCash, pay it back in 50 days, pay nothing extra,” that plan fails. You will pay interest for all 50 days. The interest-free benefit is for spending at merchants, not for turning your limit into pocket money.
Two other things to watch:
- Minimum payment. Pay at least the monthly minimum or Salmon temporarily locks your credit line until you settle. Missing it also adds late fees.
- Payment partner fees. Repaying inside the Salmon app is free, but some third-party payment channels may charge their own fees.
Salmon Credit Line vs Credit Card
For a Filipino without a traditional bank credit card, Salmon fills a real gap. Big-bank cards often ask for payslips, an ITR, a minimum income, and weeks of waiting. Salmon uses an AI-powered credit engine built for people with thin credit histories and returns a decision in minutes.
| Salmon Credit Line | Typical Bank Credit Card | |
|---|---|---|
| Annual fee | None | Often ₱1,500 to ₱5,000, sometimes waived |
| Approval time | As fast as 10 minutes | Days to weeks |
| Requirements | App-based, profile-driven | Income docs, often minimum salary |
| Grace period | Up to 62 days on purchases | Typically around 50 to 52 days |
| Acceptance | QR Ph plus Visa/Mastercard via Salmon Card | Visa/Mastercard/JCB/Amex networks |
| Rewards/points | Not the main selling point | Points, miles, cashback common |
| Starting limit | Grows with usage and on-time payment | Based on declared income |
The trade-off: you give up rewards programs and premium perks, but you skip the paperwork and the annual fee. Your limit also grows the more you use the line and pay on time, which doubles as a way to build a credit record.
Is Salmon Bank Legit? What Changed in 2026
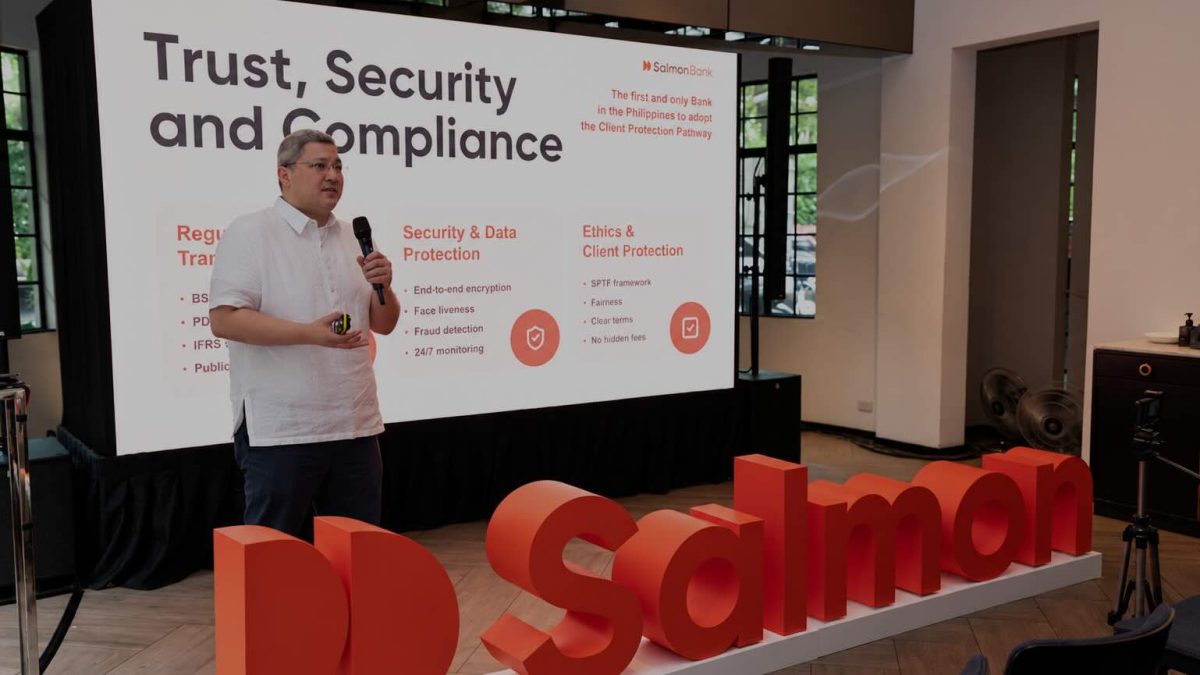
Fair question for any app asking for your money. Salmon Group runs two regulated entities. Salmon Bank (Rural Bank) Inc. holds a Bangko Sentral ng Pilipinas license and was formerly the Rural Bank of Sta. Rosa (Laguna), which has served Filipinos since 1963. Salmon Finance Inc. holds an SEC license and handles the lending side, including the credit line.
The company has also been busy this year:
- March 2026: Salmon Group injected ₱400 million into Salmon Bank, bringing equity capital to ₱1.6 billion. Management has said it wants ₱2 billion before the end of 2026 so it can apply for a thrift bank license.
- April 2026: a US$100 million financing round, with the equity led by Spice Expeditions.
- May 2026: leadership reshuffle. George Chesakov stays President and CEO, co-founder Raffy Montemayor moves to Deputy CEO, and compliance chief Eunice Monsod becomes Chairperson.
- October 2026: another US$140 million (US$90 million equity, US$50 million bonds) to grow the Credit Line and store loans, and to launch motorcycle and MSME loans nationwide.
The Salmon app Philippines users download holds a 4.8 rating on both the App Store and Google Play. Ratings are not audits, but combined with BSP and SEC licensing and heavy institutional backing (IFC of the World Bank Group is an investor), Salmon reads as a real, regulated player, not a fly-by-night lending app.
Salmon Bank PDIC Insured Deposits and Time Deposit Rates
The credit line gets the headlines, but the deposit side is what drove Salmon Bank’s growth. Its depositor base more than doubled in 2025, pulled in largely by high time deposit rates.
Yes, Salmon Bank PDIC insured status is confirmed: deposits are covered up to ₱1 million per depositor, and joint accounts are insured separately.
Current Salmon Bank time deposit rate structure, based on its published pages:
| Product | Rate | Notes |
|---|---|---|
| Regular Savings | 3% p.a. | Demand deposit earns nothing |
| Time Deposit | 6% to 8% p.a. | Depends on amount and term |
| “Bank On Eight” promo | 8% p.a. | Minimum ₱1 million, minimum 1-year term |
| Early withdrawal | 1% p.a. | Pre-termination drops your rate |
Remember the 20% final withholding tax on matured time deposit interest. An 8% gross rate nets you 6.4% after tax, still well above what most big banks pay on savings. Do not park money you might need before maturity, because pre-termination cuts your rate to 1%.
How to Apply for Salmon Credit Line
- Download the Salmon app from Google Play, the App Store, or Huawei AppGallery.
- Tap “Get started” and register an active Philippine mobile number.
- Complete the in-app application and identity verification.
- If approved, review and sign your Credit Line Agreement using an OTP.
- Start spending via QR Pay or link your virtual or physical Salmon Card.
Existing Product Loan customers with a clean payment record may get offered a credit line without a separate application.
TechPatrol Verdict
This Salmon credit line review comes down to one rule: use it like a card, not like a loan. Treat QR Ph and Salmon Card purchases as a 30-to-62-day float you clear in full every statement, and the product costs you nothing. Treat it as an instant cash source to fund your GCash, and it becomes an ordinary interest-bearing loan with a friendly interface.
For the unbanked or under-banked Filipino who keeps getting rejected for a bank card, Salmon is one of the better entry points right now: licensed, well-funded, and transparent about how its grace period works. For heavy spenders chasing points and lounge access, a traditional card still wins. Check the rate and fees on your own offer before you sign, since Salmon prices each customer individually.
This article is for information only and is not financial advice. Rates and terms may change; verify inside the Salmon app before applying.
Frequently Asked Questions
What is the Salmon Credit Line Philippines interest-free period? Up to 62 days on purchases made through QR Ph or the Salmon Card, provided you pay your full statement balance by the due date. Purchases made later in the billing cycle get fewer interest-free days.
What is the Salmon credit line interest rate? Salmon sets the rate per customer based on profile and credit history, and shows it in your offer before you sign. You only pay interest on the amount you use.
Do I pay interest on a Salmon credit line cash transfer to GCash? Yes. Transfers to banks or e-wallets count as cash transactions and accrue interest from the day of the transfer, with no grace period.
What is the Salmon credit line credit limit? Up to ₱250,000. Your starting limit depends on your profile and can increase as you use the line and pay on time.
Is Salmon Bank legit and PDIC insured? Yes. Salmon Bank (Rural Bank) Inc. is BSP-licensed, and its deposits are PDIC-insured up to ₱1 million per depositor. The lending arm, Salmon Finance Inc., is SEC-licensed.
What is the Salmon Bank time deposit rate? Between 6% and 8% per annum depending on amount and term, with the 8% “Bank On Eight” rate requiring at least ₱1 million locked for one year or more.